Senior freeze benefits can limit or delay property tax increases for eligible older homeowners.
If rising property taxes are putting pressure on your budget, learning what are senior freeze benefits can help you plan with more confidence. These programs vary by state, county, and city, but the basic idea is simple: they protect qualifying seniors from some future increases in their property tax bill. This guide explains how senior property tax freezes work, who may qualify, what they cover, and where people often make mistakes.
What Are Senior Freeze Benefits?
Senior freeze benefits are property tax relief programs for older homeowners. They may freeze the taxable value of a home, limit future tax increases, or delay part of a tax bill until the home is sold or the owner dies.
The word “freeze” can be confusing. In many places, a senior freeze does not mean your entire property tax bill will never change. It may freeze only the assessed value, the tax amount, or the increase caused by rising home values.
Common goals of senior freeze benefits include:
• Making housing costs easier to manage on a fixed income
• Protecting seniors from sharp increases in home values
• Helping older adults remain in their homes
• Reducing financial stress caused by local property taxes
• Providing tax relief based on age, income, disability, or home ownership
Each local program has its own rules. Some are run by a state department of revenue. Others are managed by a county assessor, township, or city tax office.

How a Senior Property Tax Freeze Works
A senior property tax freeze usually begins with an application. You submit proof of age, income, ownership, and residency. If approved, the program applies a tax benefit to your home for a specific tax year or future period.
There are several common ways these programs work:
Freezing the assessed value
A government office may freeze the assessed value of your property at a set level. If the market value of nearby homes rises, your taxable value may not rise in the same way.
This does not always freeze your final tax bill. Local tax rates can still change. New voter-approved taxes, special assessments, or changes in local budgets may also affect what you owe.
Limiting tax increases
Some programs place a ceiling on how much your property tax can rise each year. For example, a qualifying homeowner may receive protection from tax increases above a set limit.
The exact limit may depend on income or household status. A lower-income homeowner may receive more help than someone with a higher income.
Deferring property taxes
A tax deferral program lets you postpone payment rather than remove the tax. The unpaid amount may become a lien on the property and may need to be paid when you sell the home, move, refinance, or die.
Deferral can help with monthly cash flow, but it is not always free money. Interest or administrative charges may apply.
Main Senior Freeze Benefits
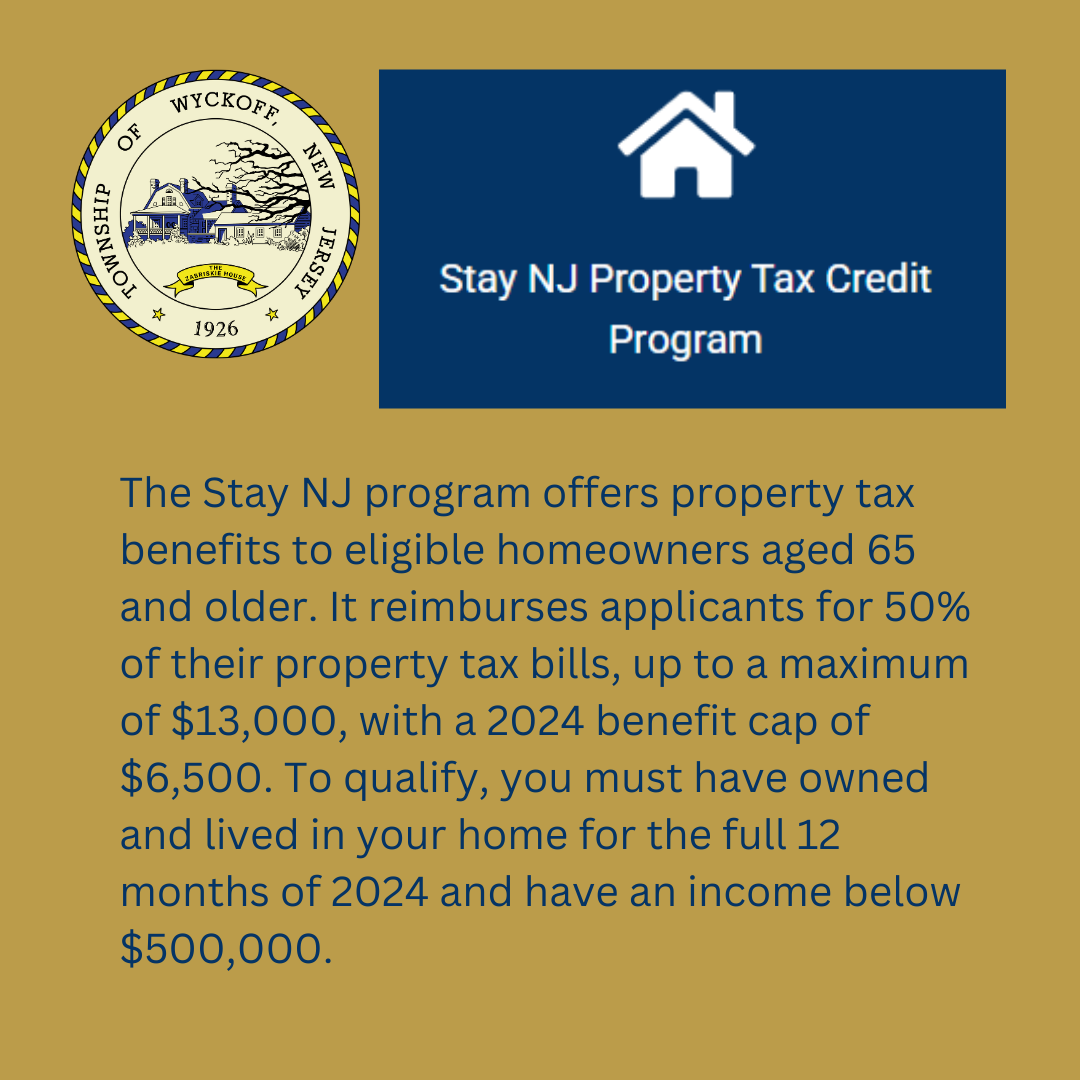
The value of senior freeze benefits depends on your local rules and your personal situation. For some homeowners, the benefit may save hundreds of dollars each year. For others, it may mainly prevent an unexpected increase.
Here are the most common benefits.
More predictable housing costs
A freeze can make your annual tax bill easier to estimate. This matters when your income comes from Social Security, a pension, or retirement savings.
Predictable costs also make it easier to create a monthly budget. Even a small tax increase can be hard to absorb when most of your income is already committed to food, medicine, utilities, and insurance.
Protection from rising home values
Home values can rise quickly, even when a homeowner’s income does not. A tax freeze may reduce the effect of those increases on your taxable value.
Think of it as a shield between market growth and your day-to-day budget. The home may be worth more on paper, but your tax assessment may receive some protection.
Support for aging in place
Many seniors want to stay in a familiar home near friends, family, doctors, and community services. Lower property taxes can make that choice more realistic.
This is especially important for homeowners who have paid off their mortgage but still face rising costs. Property taxes do not disappear when a mortgage ends.
Lower financial stress
Tax notices can feel overwhelming. A senior freeze may reduce the fear of losing financial control after a large assessment increase.
The benefit is not only about dollars. It can also provide peace of mind and reduce the need to make difficult choices between housing and health care.
Possible savings over many years
A small yearly reduction can grow into meaningful savings over time. For example, saving $500 per year could equal $5,000 over a decade, before considering changes in tax rates or eligibility.
The actual amount will depend on your property, tax district, program formula, and future changes. Ask your local tax office for an estimate instead of relying on a general example.

Who Usually Qualifies?
Eligibility for senior freeze benefits varies widely. Age is often the first requirement, but it is rarely the only one.
Common requirements include:
• Reaching a minimum age, often 65 or older
• Owning the home or holding a qualifying legal interest in it
• Using the property as your primary residence
• Meeting a household income limit
• Filing an application by the annual deadline
• Living in the home for a required period
• Providing proof of age, ownership, and income
Some programs allow a surviving spouse to continue receiving the benefit. Others provide separate relief for people with disabilities, veterans, or low-income households.
The meaning of “income” can also differ. One program may count Social Security, pensions, interest, and withdrawals from retirement accounts. Another may exclude part of a payment or use adjusted gross income from a tax return.
Do not assume that owning a home outright guarantees approval. Many programs still require an income test, an occupancy test, or yearly renewal.
What Does a Senior Freeze Cover?
This is one of the most important questions to ask. A senior freeze may cover only one part of your property tax calculation.
Depending on local law, it may affect:
• The assessed value of your primary home
• The taxable value after exemptions
• A portion of the annual property tax increase
• County or municipal property taxes
• School district taxes
• Special assessments or voter-approved charges
Some charges may remain outside the freeze. Examples can include garbage fees, sewer charges, drainage fees, local improvement costs, and special district assessments.
A tax exemption is also different from a tax freeze. An exemption lowers the taxable value or removes part of the tax. A freeze protects against certain future increases. Some homeowners can receive both, while others must choose one program.
Always read the approval notice carefully. It should explain what is frozen, the effective tax year, and the events that can end the benefit.
Senior Freeze Benefits Versus Other Tax Relief
Understanding the difference between programs can prevent costly confusion. Local offices may use similar terms for very different forms of assistance.
Senior property tax exemption
An exemption reduces the taxable value of a home. It may be available based on age, income, disability, military service, or other factors.
An exemption usually lowers the current tax bill. It may not protect you from future increases in the same way as a freeze.
Property tax circuit breaker
A circuit breaker limits property taxes based on income. If your tax bill takes up too much of your household income, you may receive a credit or reduction.
This program may be available to renters as well as homeowners, depending on the state.
Property tax deferral
A deferral postpones payment. The amount owed may grow over time and can become a lien against the property.
Deferral can be useful when cash is tight, but you should understand the repayment terms before signing up.
Homestead exemption
A homestead exemption often reduces the taxable value of a primary residence. It may be available to homeowners of many ages.
Some seniors qualify for both a homestead exemption and a senior freeze. The local assessor can tell you whether the benefits can be combined.
How to Apply for Senior Freeze Benefits
The application process is usually manageable, but missing a deadline can cost you a year of relief. Start early and keep copies of everything you submit.
Follow these steps:
-
Find the correct local office. Check your county assessor, tax collector, township, or state revenue department.
-
Confirm the program name. The benefit may be called a senior freeze, senior tax relief, assessment freeze, tax cap, or property tax deferral.
-
Review the eligibility rules. Pay close attention to age, income, ownership, residency, and filing deadlines.
-
Gather your documents. You may need a government ID, deed, tax bill, income records, Social Security statement, pension statement, and proof of residence.
-
Submit the application. Use the official form and keep a dated copy for your records.
-
Check the approval notice. Make sure your name, address, tax year, and benefit type are correct.
-
Ask about renewal. Some programs renew automatically, while others require a new application every year.
One practical lesson is to avoid waiting for the tax bill before asking questions. By then, the application deadline may have passed. A short call to the assessor’s office early in the year can prevent a major mistake.

Common Mistakes to Avoid
Many eligible homeowners miss senior freeze benefits because of simple errors. The rules can be strict, but most problems are avoidable.
Missing the deadline
Some programs accept late applications only in limited cases. Mark the deadline on your calendar and apply several weeks early.
Assuming approval lasts forever
A change in income, ownership, marital status, or residence may affect eligibility. Some programs require annual renewal even when nothing has changed.
Forgetting to report a move
A senior freeze usually applies to your primary residence. Renting out the home, moving to another state, or buying a new property may end the benefit.
Misunderstanding income rules
Do not guess how the program counts income. Ask whether it includes retirement withdrawals, tax-exempt interest, support from family members, or a spouse’s income.
Believing every tax charge is frozen
A freeze may not cover special assessments or local fees. Compare the approval letter with the full tax bill.
Paying a company for basic help
Some private companies charge fees to complete forms that are available for free from a government office. Be careful with anyone who promises approval or asks for urgent payment.
A Simple Example
Imagine that Maria is 68 and owns a home in her county. Her home’s assessed value rises from $180,000 to $205,000. Without relief, that increase could raise her property tax bill.
Maria applies for the local senior freeze program. The rules allow her assessed value to remain at $180,000 for the qualifying portion of her tax calculation. Her bill may still change if the tax rate rises or if a new special assessment is added.
This example shows why the phrase “tax freeze” needs careful review. Maria receives protection, but not necessarily a guarantee that her total bill will stay exactly the same.
Are Senior Freeze Benefits Worth It?
For many eligible homeowners, senior freeze benefits are worth applying for because the application is often free and the potential savings can last for years. The benefit is especially valuable when property values are rising faster than household income.
Still, the right choice depends on the program. A deferral may help today but create a future lien. A freeze may offer less relief than an exemption. A circuit breaker may be better for a homeowner with a very low income.
Before applying, compare:
• The amount of expected savings
• Whether the benefit must be renewed
• Whether taxes or interest are deferred
• What happens after a sale or move
• Whether the benefit affects heirs
• Whether you can combine it with other exemptions
A local tax professional, legal aid office, or assessor can help explain the rules. Be cautious about paying for advice when free public assistance is available.
Practical Tips for Getting the Most Value
A few simple habits can make the process smoother.
Keep a folder with your tax bills, approval letters, applications, and income documents. Digital copies are useful, but paper copies can help if an online account changes.
Review your property record each year. Check the owner name, mailing address, assessed value, and exemptions. Report errors promptly.
If you recently inherited a home, added a spouse to the deed, or moved into a new residence, ask how the change affects your benefit. Property ownership rules can be complex.
You can also ask the tax office these questions:
• What exactly does the freeze protect?
• Does it cover school and special district taxes?
• Is there an income limit?
• Do I need to renew each year?
• Will the benefit continue for a surviving spouse?
• Does the program create a lien or require repayment?
Clear questions often lead to clear answers. Do not rely on a neighbor’s experience because two nearby properties may fall under different taxing authorities.
Frequently Asked Questions About What Are Senior Freeze Benefits
What are senior freeze benefits designed to do?
Senior freeze benefits are designed to protect eligible older homeowners from certain property tax increases. They may freeze an assessed value, limit a tax increase, or delay payment under local rules.
Do senior freeze benefits freeze the entire property tax bill?
Not always. A program may leave tax rate changes, special assessments, school taxes, or local fees outside the freeze, so your total bill can still change.
What age do you need to qualify for a senior property tax freeze?
The minimum age depends on the program. Many programs use age 65, but some require a different age or offer separate rules for disabled homeowners and surviving spouses.
Do you have to own your home to receive senior freeze benefits?
Most homeowner freeze programs require ownership or a qualifying legal interest in the property. Some other property tax relief programs may help renters, so check your local rules.
Is a senior property tax freeze the same as an exemption?
No. An exemption usually lowers the taxable value or removes part of the tax. A freeze generally protects against certain future increases, although some programs may allow both benefits.
Can your income affect eligibility?
Yes. Many programs use an income limit, and the definition of income varies by location. Ask the administering office which payments and retirement funds count.
Do senior freeze benefits need to be renewed?
Some programs renew automatically, while others require an application every year. Review your approval notice and contact the local tax office before the next filing deadline.
What happens when you sell a home with a tax freeze?
The benefit usually ends when you sell, move, or stop using the property as your primary residence. If you used a deferral program, the unpaid amount may become due at that time.
Conclusion
Senior freeze benefits can make property taxes more manageable for older homeowners, but the details matter. A freeze may protect your assessed value, limit increases, or delay payment, yet it may not cover every charge on your tax bill.
Start by contacting your county or state tax office. Confirm the age and income rules, gather your records, and apply before the deadline. Take time to compare a freeze with exemptions, circuit breakers, and deferrals so you choose the option that fits your budget. Explore your local relief programs today, and share this guide with a senior homeowner who may benefit from it.
Michael Reynolds is a senior contributor at RetirementGazette.com, where he focuses on helping readers navigate the journey toward a secure and fulfilling retirement. With over a decade of experience in personal finance, retirement planning, and lifestyle writing, Michael combines practical strategies with easy-to-understand guidance tailored for both pre-retirees and those already enjoying their golden years.