A senior usually qualifies for Medicaid by meeting age, income, asset, residency, and care needs rules.
How does a senior qualify for Medicaid? The answer depends on the state, the type of care needed, and whether the person seeks help with medical bills, home care, or nursing home costs. Medicaid rules can feel like a maze, but the path becomes clearer when you separate income, assets, health needs, and application steps. This guide explains the process in plain English, highlights common mistakes, and shares practical ways to prepare a strong application.
What Is Medicaid for Seniors?
Medicaid is a joint federal and state program that helps eligible people pay for health care. Each state runs its own program within federal rules, so eligibility can differ across the country.
For seniors, Medicaid may help pay for:
• Doctor visits and hospital care
• Prescription drugs through Medicare Part D support
• Nursing home care
• Home health services
• Personal care assistance
• Medical transportation
• Dental, vision, or hearing services, depending on the state
• Medicare premiums and other cost sharing
Many seniors have both Medicare and Medicaid. This is called dual eligibility. Medicare usually pays first for covered medical care, while Medicaid may help with premiums, deductibles, services Medicare does not cover, and long term care.
A useful way to think about the programs is this: Medicare is mainly based on age or disability and work history. Medicaid is based mainly on financial need and state eligibility rules.
So, how does a senior qualify for Medicaid? The person must usually meet the state’s rules for age, income, assets, immigration or citizenship status, and residency. Additional rules may apply when the person needs nursing home care or home and community based services.
How Does a Senior Qualify for Medicaid?
How does a senior qualify for Medicaid in most states? A person aged 65 or older normally applies under the aged, blind, or disabled category. The state then reviews financial and nonfinancial requirements.
The main factors include:
Age or disability
Most senior Medicaid pathways begin at age 65. A person under 65 may qualify through disability or another Medicaid group.
State residency
The applicant must live in the state where the application is filed. The person does not always need to live in the state for a set period, but the state must consider it the person’s home.
Citizenship or qualified immigration status
U.S. citizens may qualify if they meet the other rules. Some qualified noncitizens may also qualify, but immigration rules can be complex and may include waiting periods.
Countable income
The state reviews income such as:
• Social Security retirement benefits
• Supplemental Security Income
• Pension payments
• Wages
• Annuities
• Interest and dividends
• Rental income
• Some distributions from retirement accounts
Countable assets
The state may review resources such as:
• Bank accounts
• Cash
• Stocks and bonds
• Certificates of deposit
• Some retirement funds
• A second vehicle
• Extra real estate
The exact rules vary. A primary home, one vehicle, household goods, and personal items may receive an exemption. However, an exempt asset can become relevant later, especially through estate recovery.
Medical or care needs
Medical need is especially important for nursing home Medicaid and some home care programs. A senior may need help with daily activities such as bathing, dressing, eating, toileting, or moving from a bed to a chair.
Not every Medicaid program requires the same level of care. Regular health coverage and long term care coverage often use different tests.
Medicaid Income Limits for Seniors
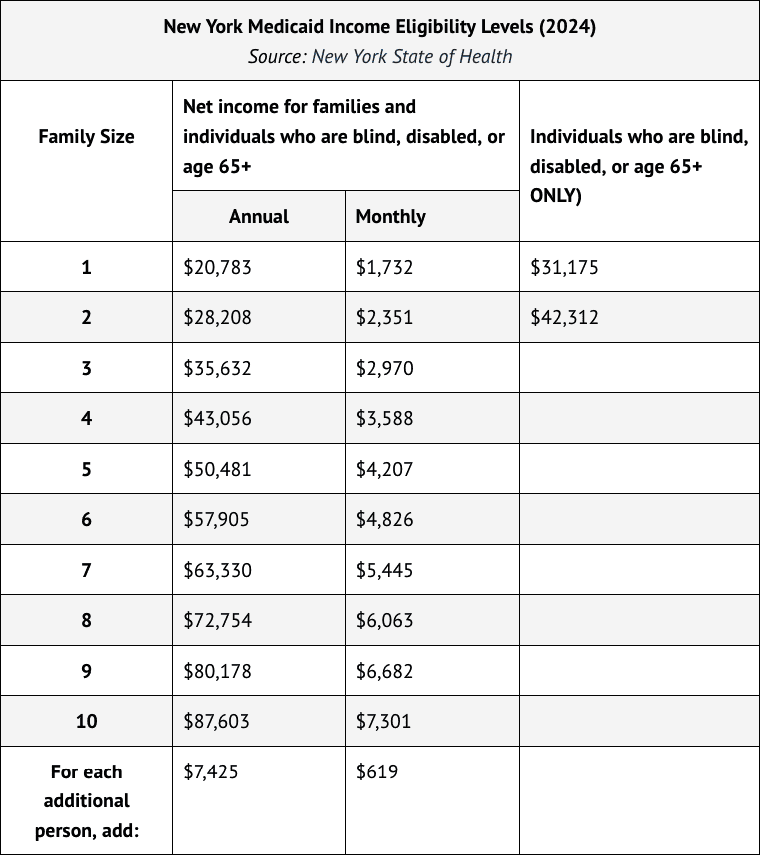
Income limits are one of the most confusing parts of senior Medicaid eligibility. There is no single national income limit that applies to every senior in every situation.
States often use a monthly income limit for aged, blind, and disabled Medicaid. The limit may be tied to the Federal Poverty Level, a state standard, or a special institutional care rule.
Countable income may include:
• Social Security
• SSI
• Pension income
• IRA withdrawals
• Annuity payments
• Earnings from work
• Interest income
• Rental income
Some income may be excluded. Examples can include certain work expenses, limited personal needs allowances, or payments that state rules do not count.
A senior who earns slightly more than the standard limit may still have options. Some states allow a medically needy pathway. Under this system, a person may spend part of their income on approved medical costs before qualifying.
Other states use a Qualified Income Trust, sometimes called a Miller Trust, for certain nursing home applicants. The trust usually directs excess income into an account managed under strict state rules. It must be prepared correctly, and the rules differ by state.
Do not assume that being over the income limit means Medicaid is impossible. Ask the state Medicaid office or a qualified elder law attorney about medically needy rules, income deductions, and trust options.
How Social Security affects eligibility
Social Security usually counts as income for Medicaid. The state may look at the gross benefit before certain deductions rather than only the amount deposited in the bank.
For example, a senior may receive $1,900 in Social Security but see a smaller deposit after a Medicare premium is deducted. The Medicaid agency may use the larger gross amount when testing eligibility.
This is one reason to keep benefit letters and Medicare notices. They help explain the numbers on the application.

Medicaid Asset Limits for Seniors
Assets are also called resources. A senior may need to stay under a state resource limit to qualify for certain Medicaid programs.
Countable resources often include:
• Checking and savings accounts
• Cash
• Brokerage accounts
• Stocks and bonds
• Some retirement accounts
• Vacation homes
• Extra vehicles
• Property that is not exempt
The state may exclude or partly exclude:
• A primary residence, subject to home equity rules
• One vehicle used for transportation
• Household goods
• Clothing
• Personal belongings
• Burial spaces
• Certain prepaid burial arrangements
• Some low value life insurance policies
Asset rules can become difficult when a senior is married. Medicaid may protect some resources for the spouse who remains at home. This protection is often called a spousal resource allowance.
A married couple should not assume that every account is treated as half of the total. Ownership, account type, state law, and the date of application can affect the calculation.
A simple example
Imagine a senior has:
• $1,800 in monthly Social Security
• $2,000 in a checking account
• A modest home
• One older car
• $18,000 in an IRA
The state may count the bank account and IRA. It may exclude the home and one vehicle if they meet state rules. The final result depends on the Medicaid category and the state’s treatment of retirement funds.
The lesson is simple: do not hide, give away, or retitle assets without advice. A transfer that seems harmless can create a penalty or delay.
How Nursing Home Medicaid Rules Differ
How does a senior qualify for Medicaid when nursing home care is needed? The financial test is only part of the process. The applicant must usually show a medical need for a nursing facility level of care.
The state may review:
• Doctor’s records
• Diagnoses
• Medication needs
• Cognitive limitations
• Falls or safety risks
• Help needed with daily activities
• Skilled nursing needs
• The need for supervision
A senior does not always need to be bedridden. Dementia, repeated falls, severe weakness, or the need for regular clinical care may support eligibility.
Nursing home Medicaid often has special income rules. The senior may be required to contribute most monthly income toward the cost of care, while keeping a small personal needs allowance. The exact amount varies by state.
The spouse at home may receive protections for income and resources. These rules are designed to prevent the community spouse from becoming financially dependent on Medicaid after the other spouse enters a nursing facility.
The five year lookback period
Many states review asset transfers made during the five years before a nursing home Medicaid application. This is commonly called the five year lookback period.
The state may ask for records showing:
• Bank transfers
• Gifts to relatives
• Property sales
• Trust funding
• Annuity purchases
• Large cash withdrawals
If the senior gave away assets for less than fair market value, the state may impose a period of Medicaid ineligibility. The penalty is based on the value transferred and the state’s calculation method.
This does not mean every transfer causes a penalty. Certain transfers may be allowed, such as some transfers to a spouse or a disabled child. Because the details matter, professional advice is important before moving money or property.
Home and Community Based Medicaid Services
Many seniors want to remain at home. Medicaid may offer home and community based services, often called HCBS, for people who meet financial and care requirements.
Services may include:
• Personal care aides
• Help with bathing and dressing
• Adult day care
• Respite care for family caregivers
• Home delivered meals
• Transportation
• Case management
• Medical equipment
HCBS programs often have enrollment caps or waiting lists. A senior may qualify financially but still wait for a specific service.
The care assessment is important. Keep a clear record of what the senior cannot safely do alone. Notes from a caregiver can help show patterns that a short doctor visit may not reveal.
For example, “needs help sometimes” is less useful than “fell twice this month and needs hands on help to bathe.” Honest, specific details give the assessor a clearer picture.
How Medicare and Medicaid Work Together
Medicare and Medicaid serve different purposes, but they can work together.
Medicare often pays for:
• Hospital stays
• Physician services
• Short term skilled nursing care
• Medicare covered prescriptions
Medicaid may help with:
• Medicare Part B premiums
• Medicare deductibles and coinsurance
• Long term nursing home care
• Personal care services
• Some dental, vision, and hearing care
A senior may qualify for a Medicare Savings Program even if full Medicaid is not available. These programs can help pay Medicare premiums and other costs.
The main Medicare Savings Program groups include:
• Qualified Medicare Beneficiary
• Specified Low Income Medicare Beneficiary
• Qualifying Individual
• Qualified Disabled and Working Individual
Each group has its own income and asset rules. Some states have expanded or changed these limits, so current state information matters.
How does a senior qualify for Medicaid while already receiving Medicare? The senior must submit a Medicaid application and meet the state’s financial and care rules. Medicare enrollment does not automatically create Medicaid eligibility.
Documents Needed for a Medicaid Application
Good records can make the application process much smoother. Medicaid agencies may request information from several months or even several years, especially for long term care.
Gather:
• Social Security award letters
• Pension statements
• Recent bank statements
• Retirement account statements
• Life insurance policies
• Property tax records
• Deeds and mortgage documents
• Vehicle titles
• Annuity contracts
• Trust documents
• Medical records
• Nursing home bills
• Medicare cards
• Proof of citizenship or immigration status
• Marriage, divorce, or death certificates when relevant
Keep copies of everything submitted. Write down the date, the agency name, and the person you spoke with. If the agency requests more information, respond by the deadline.
A common mistake is sending only the current bank statement. The agency may need a full history. Missing statements can slow the decision or lead to a denial.
Step by Step: Applying for Medicaid as a Senior
How does a senior qualify for Medicaid without getting lost in paperwork? Follow a simple process.
- Identify the type of Medicaid needed
Decide whether the goal is help with medical bills, Medicare costs, home care, assisted living support, or nursing home care. Different programs may use different rules.
- Check the state’s current rules
Visit the official state Medicaid website or contact the state Medicaid office. Ask for rules for aged, blind, or disabled adults and for long term care if needed.
- Gather financial records
Collect income statements, account histories, property records, insurance documents, and transfer information. Do not wait until a crisis forces a rushed application.
- Complete the application
Apply online, by mail, by phone, or in person, depending on the state. A legal representative may apply if properly authorized.
- Complete the care assessment
For home care or nursing home coverage, provide honest details about daily assistance and safety needs.
- Answer follow up requests
The agency may ask for missing records or clarification. Respond quickly and keep proof of delivery.
- Review the decision
If the state denies coverage, read the notice carefully. It should explain the reason and appeal deadline.
- Appeal when appropriate
A denial may result from missing paperwork, an incorrect income calculation, or a misunderstanding about assets. An appeal can correct these errors.
When professional help makes sense
Consider speaking with an elder law attorney, Medicaid planner, or benefits counselor when:
• Nursing home care is involved
• A spouse remains at home
• The senior owns a business or rental property
• There are recent gifts or transfers
• A trust or annuity is involved
• The person received an inheritance
• The application was denied
Free or low cost help may be available through a State Health Insurance Assistance Program, an Area Agency on Aging, or a legal aid office.
Common Medicaid Mistakes Seniors Should Avoid
Medicaid mistakes can cause stress and delays. Some can also create serious financial problems.
Giving money away before applying
A gift to a child may count as a disqualifying transfer for long term care Medicaid. Even a payment made with good intentions can raise questions.
Hiding an account
Failing to report an account can lead to denial, loss of benefits, or recovery action. Report the account and explain ownership clearly.
Adding a child to a bank account
A joint account may create confusion about who owns the funds. It can also affect future eligibility and estate recovery.
Selling property for less than fair value
A below market sale may look like a gift. Keep an appraisal, contract, and proof of payment for any major transaction.
Waiting until the nursing home bill is overwhelming
Medicaid applications can take time. Start early when a doctor or family member believes long term care may be needed.
Assuming Medicare pays for long term care
Medicare may cover limited skilled nursing care after a qualifying hospital stay, but it does not usually cover ongoing custodial nursing home care. Medicaid is often the main public payer for long term nursing home services.
Trusting outdated online limits
Income and asset limits change. Use current state information rather than relying on a chart from several years ago.
A practical lesson from many family cases is to keep financial records organized before a crisis. A simple folder with statements, policies, deeds, and benefit letters can save weeks of confusion.
Medicaid Estate Recovery
Medicaid estate recovery allows a state to seek repayment for certain Medicaid benefits paid after a beneficiary dies. Recovery often applies to nursing home care, home and community based services, and related costs for people who were at least 55.
The rules vary by state. Recovery may involve the person’s probate estate, home, or other property. Some protections may apply for a surviving spouse, a minor child, or a child with a disability or blindness.
Estate recovery does not mean a senior should avoid needed care. It does mean families should understand the possible effect on a home or other property.
Ask the state Medicaid office for its estate recovery policy. An elder law professional can also explain whether a specific estate plan creates risks.
How Long Does Medicaid Approval Take?
Processing time varies by state and by the type of Medicaid requested. A basic health coverage application may move faster than a nursing home application that requires a financial review and medical assessment.
Delays often happen because:
• Bank statements are missing
• Income does not match agency records
• A transfer needs explanation
• Property ownership is unclear
• Medical records are incomplete
• The application has an incorrect date
• The agency cannot reach the applicant
To reduce delays, answer every request on time and send complete documents. Ask for a written receipt or confirmation whenever possible.
If the senior needs urgent nursing home care, ask the facility’s Medicaid specialist about the application process. The facility can often help gather records, but it cannot guarantee approval.
What to Do if Medicaid Denies the Application
A denial is not always the final answer. Read the notice and identify the exact reason.
The problem may be:
• Income above the limit
• Assets above the limit
• Missing proof
• Incorrect household information
• Failure to meet a medical need standard
• A transfer penalty
• A residency or immigration issue
If the agency made an error, request a fair hearing before the deadline in the notice. Bring documents that support your position.
For complex cases, get help from an elder law attorney or legal aid group. A benefits counselor may help with Medicare Savings Programs and other lower income options.
Do not simply submit the same application again without correcting the stated problem. First learn why the application failed, then address that issue directly.
Frequently Asked Questions About How Does a Senior Qualify for Medicaid
How does a senior qualify for Medicaid if they receive Social Security?
Social Security usually counts as income, but receiving it does not automatically disqualify a senior. The state compares the senior’s countable income and assets with the rules for the specific Medicaid program.
Can a senior qualify for Medicaid if they own a home?
Yes, a senior may qualify while owning a home if it meets the state’s home exemption rules. Home equity limits, the senior’s living arrangement, and future estate recovery may still matter.
Can a married senior qualify for Medicaid if the spouse has money?
Yes, but the state may review the couple’s income and resources under spousal protection rules. The spouse who remains at home may be allowed to keep certain income and assets.
Does Medicaid pay for nursing home care?
Medicaid can pay for nursing home care when the senior meets financial and medical eligibility rules. The senior may have to contribute most available income toward the cost of care.
Can a senior qualify for Medicaid with too much income?
Possibly. Some states offer medically needy programs, income deductions, or Qualified Income Trust options for certain applicants, especially those who need long term care.
Is there a five year Medicaid lookback period?
There is often a five year lookback for nursing home Medicaid, but the exact rule and penalty calculation depend on the state. Transfers made during that period may need to be explained.
How long does a senior Medicaid application take?
The time varies by state, program, and application complexity. Missing records, property questions, and long term care assessments can make the process take longer.
Conclusion
How does a senior qualify for Medicaid? The senior usually must meet state rules for age, income, assets, residency, citizenship or qualified immigration status, and medical or care needs. Nursing home and home care applications may also involve transfer reviews, spousal protections, and estate recovery rules.
Start by identifying the right Medicaid program, gathering complete records, and checking current state requirements. Avoid giving away money or changing ownership of property without qualified advice. For more guidance, contact the state Medicaid office, a benefits counselor, or an elder law professional, and share this guide with a family member who may need it.
Michael Reynolds is a senior contributor at RetirementGazette.com, where he focuses on helping readers navigate the journey toward a secure and fulfilling retirement. With over a decade of experience in personal finance, retirement planning, and lifestyle writing, Michael combines practical strategies with easy-to-understand guidance tailored for both pre-retirees and those already enjoying their golden years.