Seniors can save money by cutting monthly costs, using available benefits, and planning health and household spending.
Learning how can seniors save money starts with looking at the whole budget, not just one expense. Small changes to housing, food, medical care, transportation, and subscriptions can protect cash flow without making life feel smaller. This guide combines practical budgeting steps, public programs, and lessons from helping families make their money last longer.
Start with a Simple Senior Budget
A clear budget is the best starting point. Many older adults know their income, but they may not know where each dollar goes. A simple spending review can reveal bills that are no longer useful or have quietly increased.
Write down monthly income first. Include Social Security, pensions, withdrawals from retirement accounts, part-time work, rental income, and other regular payments.
Then list expenses in three groups:
• Essential costs: Housing, utilities, food, medicine, insurance, and transportation
• Flexible costs: Dining out, clothing, hobbies, gifts, and travel
• Occasional costs: Home repairs, car work, annual fees, and medical equipment
A budget does not need to be complex. A notebook, spreadsheet, or free budgeting app can work well. The key is to compare planned spending with actual spending each month.
One useful method is a “three-month money check.” Review the last three bank statements and credit card bills. Look for repeated charges, late fees, unused memberships, and spending that does not match current needs.
When people ask how can seniors save money, I often suggest starting with recurring expenses. A $20 monthly subscription may not seem important, but five unused subscriptions can cost $1,200 each year.
Reduce Housing and Utility Costs
Housing is often the largest expense in a senior household. Saving on housing does not always mean moving. It may mean lowering energy use, checking property tax relief, or choosing a safer and more affordable living arrangement.
Homeowners should check for local property tax exemptions. Many states and counties offer relief for older adults, people with disabilities, or low-income homeowners. Rules differ, so contact the local tax assessor’s office.
Renters can ask about:
• Senior apartment communities
• Income-based housing
• Local rental assistance
• Utility allowance programs
• Shared housing options
Energy costs can also fall with a few practical steps. Seal drafts around doors and windows. Replace old light bulbs with LED bulbs. Set the thermostat carefully and ask the utility company about a home energy audit.
Some utility providers offer reduced rates, payment plans, or weatherization help. Call the provider and ask about senior discounts or low-income programs. These benefits are not always advertised clearly.
Downsizing may help, but it should not be rushed. Moving costs, deposits, repairs, and emotional stress can reduce the savings. Compare the full yearly cost of the current home with the full yearly cost of the new home before making a choice.
A helpful lesson I have seen in real household planning is this: the cheapest home is not always the best home. A slightly higher rent may still save money if it lowers transportation, repair, and utility costs.
Save Money on Health Care
Health care can affect a senior budget more than almost any other category. The goal is not to skip needed care. The goal is to use coverage wisely and prevent small problems from becoming expensive ones.
Review Medicare coverage each year during the open enrollment period. Plans, premiums, drug lists, provider networks, and out-of-pocket costs can change. A plan that worked well last year may not be the best choice this year.
Free, unbiased help is available through State Health Insurance Assistance Programs, often called SHIP. A trained counselor can help compare Medicare choices without selling a plan.
Ask health care providers about:
• Generic medicines
• Lower-cost treatment options
• Payment plans
• Financial assistance
• Preventive services covered by insurance
Do not stop a medicine or change a dose without speaking with a health professional. A lower price is not helpful if a treatment becomes unsafe.
Prescription costs may fall when patients compare pharmacies, use preferred pharmacies, or ask about prescription assistance programs. Some drug manufacturers and nonprofit groups also offer help for eligible patients.
Keep a medical folder with insurance cards, medicine lists, test results, and bills. This can prevent duplicate payments and make errors easier to spot. Review every medical bill before paying it, especially after a hospital stay.
Preventive care is another form of saving. Vaccines, screenings, dental care, vision checks, and regular visits may catch problems early. Medicare coverage varies, so confirm what is included before scheduling a service.
This is one of the most important answers to how can seniors save money: protect health while managing costs. Delaying necessary care can create much larger bills later.
Lower Grocery and Food Costs
Food prices can place steady pressure on a fixed income. Seniors can save money without giving up healthy meals by planning before shopping.
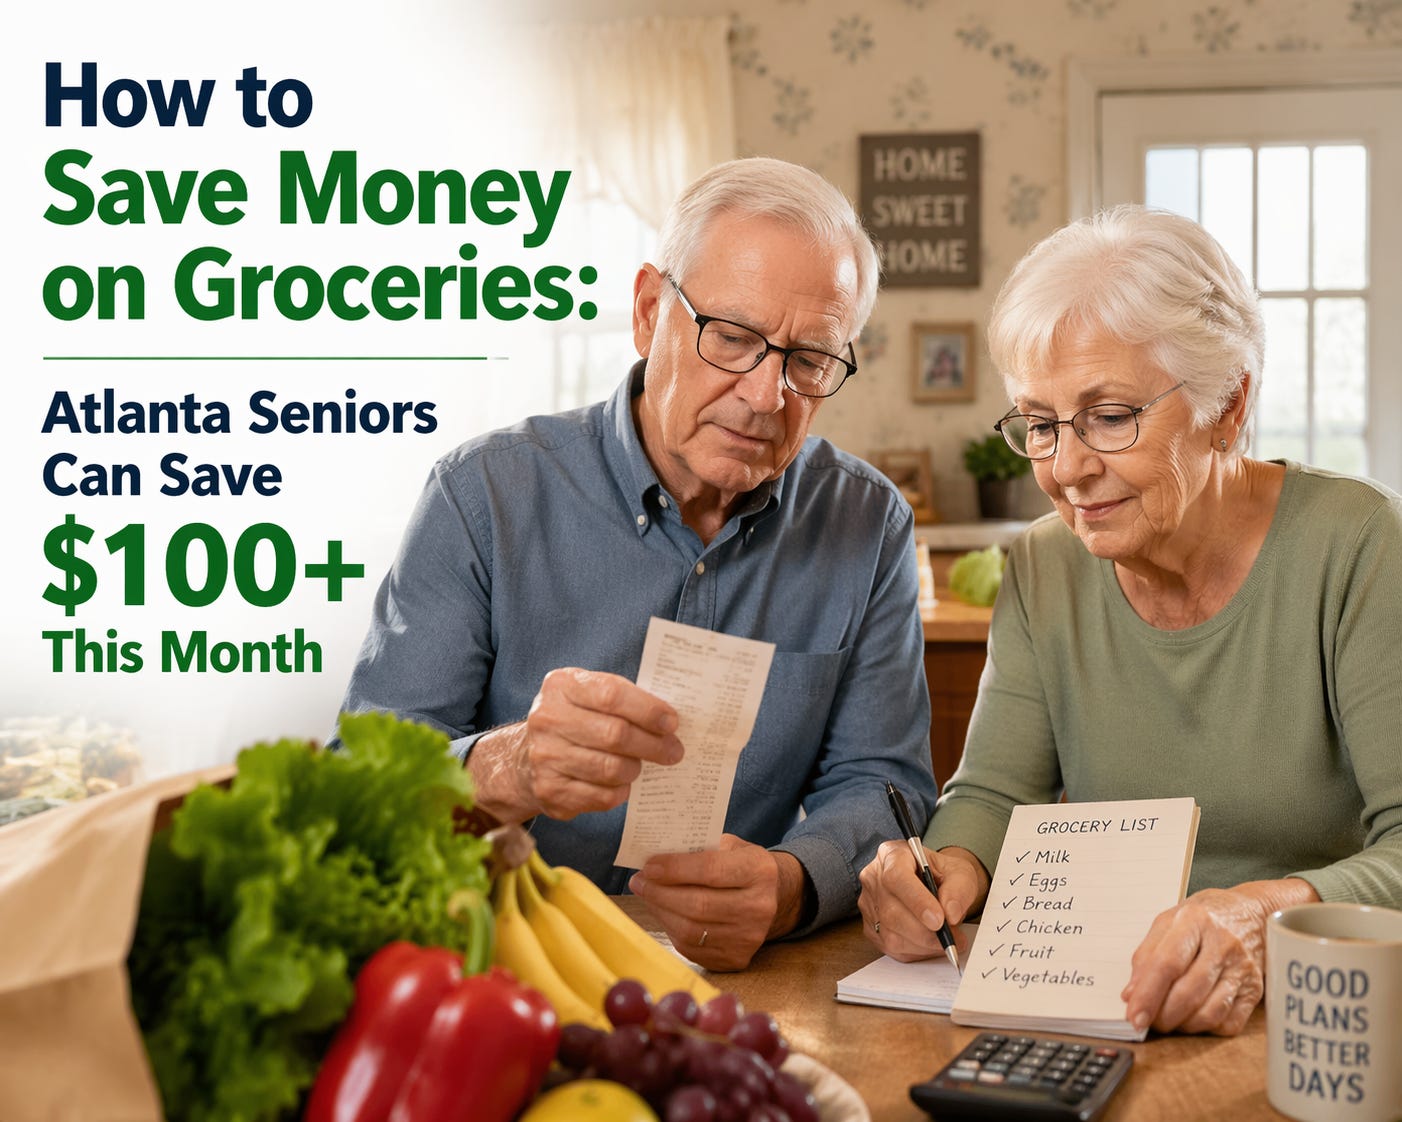
Start with a weekly meal plan. Choose a few low-cost staples, such as beans, eggs, oats, rice, frozen vegetables, canned fish, and whole-grain products. Use foods already at home before buying more.
Helpful grocery habits include:
• Make a list and follow it
• Compare unit prices, not just package prices
• Buy store brands when quality is similar
• Use frozen produce when fresh items cost more
• Avoid shopping while hungry
• Check coupons for items you already need
• Cook larger portions and freeze extra servings
Food waste is a hidden expense. Store food in clear containers, label leftovers, and freeze bread or meat before it spoils.
Many communities offer senior meal programs, food pantries, farmers market vouchers, and the Supplemental Nutrition Assistance Program, known as SNAP. Eligibility depends on income, household size, assets, and local rules.
Some older adults avoid assistance because they feel embarrassed. These programs exist to help people manage rising costs. Using a benefit you qualify for is a smart financial choice, not a personal failure.
Use Senior Discounts and Public Benefits
Discounts can help, but public benefits often create larger savings. Check eligibility before assuming a program is unavailable.
Common programs may include:
• Supplemental Security Income for some low-income adults
• Medicare Savings Programs
• Extra Help with Medicare prescription costs
• Medicaid, depending on state rules
• SNAP food benefits
• Low Income Home Energy Assistance
• Reduced public transportation fares
• Local property tax relief
• Telephone or internet assistance
Benefits can have different income and asset rules. Some programs also count household size, medical expenses, or housing costs. Contact an official government office or a trusted community agency for current details.
Ask about senior discounts for museums, public transit, parks, restaurants, hotels, and community centers. Some businesses offer discounts only on certain days or during certain hours.
Be careful with discount clubs. A membership may cost more than the savings it provides. Track the yearly fee and compare it with actual use.
A good rule for how can seniors save money is to verify every benefit through a trusted source. Do not pay a stranger to “unlock” Social Security, Medicare, or government funds.
Cut Transportation Costs
Transportation costs include more than gasoline. Car payments, insurance, repairs, registration, parking, and depreciation can make driving expensive.
Review how often the car is used. Combining errands can reduce fuel and save time. Regular tire checks and oil changes may also prevent costly repairs.
Compare car insurance at least once a year. Ask about low-mileage discounts, defensive driving discounts, and payment options. Never reduce important coverage without understanding the risk.
Other options include:
• Public transportation
• Paratransit services
• Community senior shuttles
• Volunteer driver programs
• Rideshare cost sharing
• Medical transportation benefits
Some Medicare Advantage plans offer transportation for approved medical visits, but coverage varies. Medicaid may also provide non-emergency medical transportation for eligible people.
For households with two vehicles, compare the total yearly cost of keeping both cars. Selling one vehicle may save money, but consider mobility, weather, caregiving, and emergency needs first.
Transportation planning is especially important in rural areas. A low-cost home can become expensive if every doctor visit requires a long drive.

Manage Debt, Banking, and Subscriptions
Debt can drain a fixed income quickly. Start by listing each balance, interest rate, minimum payment, and due date. Pay more toward high-interest debt when possible, while keeping minimum payments current on other accounts.
Call lenders before missing a payment. Some may offer hardship plans, lower interest rates, or changed due dates. Get any agreement in writing.
Credit card balance transfers and debt consolidation can help in some cases, but they are not automatic solutions. Fees, new interest rates, and longer repayment periods can increase the total cost.
Banking fees are another area to review. Ask about:
• Low-fee checking accounts
• Direct deposit options
• Overdraft protection
• ATM fee refunds
• Paper statement fees
• Minimum balance requirements
Cancel subscriptions that no longer provide value. Review streaming services, magazines, meal deliveries, storage units, memberships, and phone features.
One practical habit is a quarterly “bill day.” Check every recurring payment and ask whether it is still needed. This small task often produces savings without changing daily routines.
When considering how can seniors save money, reducing wasteful fees is a good first move. It does not require major lifestyle changes.
Protect Savings from Scams
Saving money is only half the job. Seniors also need to protect their money from fraud.
Common scams may involve fake Medicare calls, Social Security threats, romance schemes, phony charities, investment promises, and fake computer support. Scammers often create urgency and ask for gift cards, wire transfers, cryptocurrency, or personal information.
Use these safety rules:
• Do not share Medicare, Social Security, bank, or credit card numbers with unexpected callers
• Do not click links in suspicious messages
• Never send money to claim a prize
• Pause before making an urgent payment
• Confirm requests through an official phone number
• Discuss large financial decisions with a trusted person
Legitimate government agencies do not demand gift cards or threaten immediate arrest over the phone. If a message feels rushed or secretive, treat it as a warning sign.
Consider credit monitoring, strong passwords, two-factor authentication, and account alerts. A trusted contact may also help spot unusual activity, but financial power of attorney should be created carefully with qualified legal help.

Build a Practical Savings Plan
A savings plan should match income, health, and family needs. A person living on Social Security alone may need a different plan from someone with a pension and investment income.
Start with a small emergency goal. Even $10 or $25 set aside each week can create a cushion for medicine, repairs, or travel to a medical appointment.
Use separate savings categories for:
• Medical expenses
• Home and car repairs
• Gifts and holidays
• Travel and hobbies
• Funeral or final expenses
Keep emergency money in an insured bank or credit union account that is easy to access. Investments may offer growth, but market values can fall. Money needed soon should not depend entirely on stock market performance.
Be careful with annuities, reverse mortgages, and investment products. These tools can be useful for some people, but they may include fees, tax effects, restrictions, or risks. Speak with a qualified, fee-transparent professional before signing anything.
It also helps to involve family members in a clear plan. Share account instructions and important documents with a trusted person, while keeping control of personal information secure.
The best answer to how can seniors save money is usually a system, not one dramatic change. Review, adjust, and repeat.
Common Mistakes to Avoid
Saving money can backfire when a short-term discount creates a larger long-term cost. Watch for these common mistakes:
• Buying a large quantity of food that may spoil
• Skipping medical care to avoid a small bill
• Choosing insurance based only on the monthly premium
• Taking a loan from an unverified company
• Paying upfront for a promised government benefit
• Canceling needed home or auto insurance
• Giving financial control to someone without legal guidance
• Investing emergency savings in risky products
Ask three questions before making a money decision:
-
What is the total cost?
-
What could go wrong?
-
Can I change my mind later?
These questions are simple, but they create useful space between an offer and a decision.
How Can Seniors Save Money? Frequently Asked Questions
How can seniors save money on a fixed income?
Seniors can save money by reviewing recurring bills, applying for public benefits, reducing utility costs, and planning meals. Start with small monthly savings that do not affect health or safety.
What government programs help seniors save money?
Programs may include Medicare Savings Programs, Extra Help, SNAP, Medicaid, energy assistance, and property tax relief. Eligibility varies by state and personal circumstances, so use official agencies or trusted counselors to confirm current rules.
How can seniors save money on prescription drugs?
Ask a doctor or pharmacist about generic options, lower-cost pharmacies, preferred pharmacies, and assistance programs. Never change a prescription without medical guidance.
Is downsizing a good way for seniors to save money?
Downsizing can reduce rent, utilities, repairs, and property taxes. Compare moving costs and the full annual cost of the new home before deciding.
How can seniors save money on groceries?
Plan meals, compare unit prices, buy store brands, use frozen produce, and reduce food waste. Eligible seniors should also check SNAP, meal programs, and local food assistance.
How can seniors avoid financial scams?
Ignore unexpected requests for money or personal information. Contact the organization through a verified number, avoid rushed decisions, and ask a trusted person to review unusual offers.
Should seniors use a financial adviser to save money?
A qualified adviser may help with retirement income, taxes, investments, and estate planning. Ask how the adviser is paid, what services are included, and whether the adviser has a legal duty to put your interests first.
Conclusion
Seniors can save money by taking a calm, complete look at their budget. Lowering housing and utility costs, reviewing Medicare, planning groceries, using public benefits, reducing fees, and protecting against scams can make a real difference.
The process does not need to feel overwhelming. Choose one area today, such as canceling an unused subscription or checking eligibility for a benefit. Then review the results each month and build from there.
Share these ideas with a family member or trusted friend, and explore local senior resources for more support. Small steps can help your money last longer while preserving the comfort, care, and independence you value.
Michael Reynolds is a senior contributor at RetirementGazette.com, where he focuses on helping readers navigate the journey toward a secure and fulfilling retirement. With over a decade of experience in personal finance, retirement planning, and lifestyle writing, Michael combines practical strategies with easy-to-understand guidance tailored for both pre-retirees and those already enjoying their golden years.